Schnabel outlined three models for putting central bank money onchain, each with a different balance between native tokenisation and existing infrastructure.
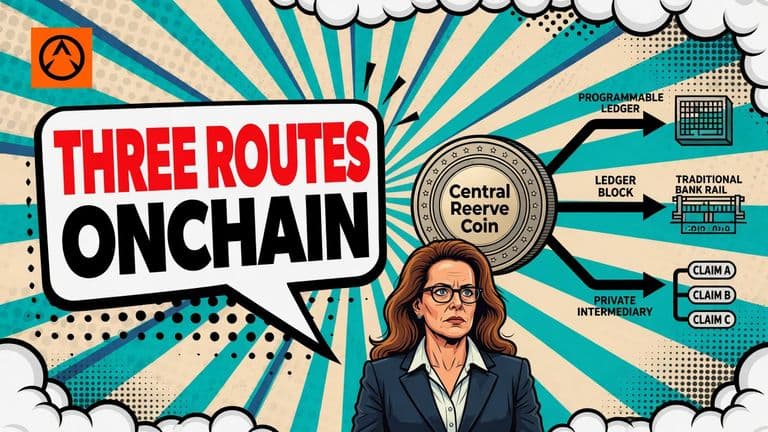
Isabel Schnabel has offered three ways to put central bank money onto distributed ledger technology. Each route gives a different answer to two practical questions: how much of the existing payments system stays in place, and who holds a claim when the token changes hands.
The options range from direct issuance of tokenised reserves to relying on a bridge or a private intermediary. For crypto users, the distinction is more than architectural. It shapes whether a tokenised asset settles directly in central bank money, through an off-chain cash leg, or against a private claim backed by reserves.
In a speech at the Jackson Hole symposium, Schnabel, a member of the ECB Executive Board, described three possible approaches.
The first is direct issuance of tokenised reserves on a programmable ledger. Only this model makes central bank reserves natively tokenised. The second connects existing payment systems to programmable platforms through bridging or synchronisation. The third uses a private intermediary to tokenise reserves for the central bank through an omnibus account.
That last model may look familiar to anyone who has examined a bank-issued token. Private parties deposit reserves with the central bank, then issue tokens backed one for one by those reserves. The token, however, is a liability under private law rather than a direct claim on the central bank.
The central bank remains passive in that arrangement. It is a balance sheet counterparty and controls eligibility, but it does not capture the technological benefits of tokenisation. If similar wrappers appear across several platforms, settlement could split into parallel private claims instead of converging around one common asset.
The direct model does more than change where the record sits. It puts the reserve itself into a form that programmable infrastructure can use.
The bridge model keeps the cash leg in traditional central bank money. A transaction may run on a DLT platform, but its central bank money component settles through an off-chain system.
That makes the bridge less radical. It connects new digital infrastructure with established payment rails without moving the final cash settlement onto the ledger.
Project Pontes is the clearest example in Schnabel's speech. It connects TARGET Services, the Eurosystem's real-time gross settlement system, with market DLT platforms. It will also include a Eurosystem-operated DLT platform for settlement in central bank money.
At launch, legal settlement finality for the cash leg will still sit with TARGET2. Schnabel expects that finality to move to the Eurosystem DLT platform later. Smart contracts and 24/7 operation are also planned for after the initial launch.
Pontes therefore has a staged design. It begins with synchronisation, then adds native tokenisation, programmability and continuous operation. A small distinction, but an important one: calling it a bridge doesn't fully describe where it is headed.
Pontes is the most directly compatible with assets that already depend on central bank settlement. It gives tokenised securities, deposits and stablecoins a route into central bank money without requiring every market participant to join one new shared ledger immediately.
For stablecoins, Schnabel's position is cautious. Their issuers cannot expand liquidity elastically, so she argues that they cannot replace central bank reserves as the economy's ultimate settlement asset. She describes them as complements to central bank money, not substitutes.
She also makes room for a carefully designed stablecoin. A floating-rate coin backed by government securities could, in principle, carry zero credit and duration risk. That would not give it the ability to supply liquidity when the system needs it.
The bridge model also carries the distinction forward. Even when the asset is tokenised and the workflow runs onchain, the cash leg still settles offchain. Pontes reduces that gap, but its launch begins with TARGET2 as the source of legal finality.
Project Appia explores a different question: what if central bank reserves and the assets traded against them share one ledger?
The project is considering three architectures:
The first design offers the cleanest settlement. If the settlement asset and the asset being exchanged sit on the same ledger, they can move in one transaction and be validated by the same consensus mechanism. This is known as atomic settlement: either the whole exchange completes or none of it does.
That could suit a broad market where tokenised deposits, securities and central bank reserves need to change hands together. The shared infrastructure would reduce the need for separate settlement systems.
It also creates one shared point of failure. Schnabel notes that a single ledger brings critical infrastructure and technology lock-in, which could limit competition and innovation. It also blurs the boundary between Eurosystem systems such as TARGET Services and privately owned infrastructure such as Euroclear and Clearstream.
A common ledger makes settlement simpler on the inside, but the institutional design behind it becomes harder to separate.
Schnabel's preferred direction is clear: central banks should use DLT themselves rather than depend on bridges or intermediaries. Direct issuance preserves central bank money as the settlement asset and captures more of what programmability can offer.
That doesn't make one architecture suitable for every asset. Pontes offers a route between existing systems and a future Eurosystem ledger. Appia tests whether central bank reserves can share infrastructure with the assets exchanged against them. The intermediary model keeps issuance private, but changes the nature of the claim and risks producing several versions of settlement.
The useful choice may depend on what a market already holds and what it needs to settle. Native tokenisation is the common destination. The three models differ mainly in how much of today's infrastructure has to move to get there.
US bank policy has shifted with leadership. A statutory framework could make Bitcoin custody and settlement rules more durable.
 BTC
SEC staff FAQs explain how token classification, staking receipts and buybacks are treated, but they cannot create new legal obligations.

An SF Fed study finds stablecoin issuers have added $200 billion in Treasuries, changing who supports the dollar debt market.

