Stablecoins Become a Bigger Buyer of Short-Term Treasuries
An SF Fed study finds stablecoin issuers have added $200 billion in Treasuries, changing who supports the dollar debt market.

By Pallavi Malviya GuptaChief Editor
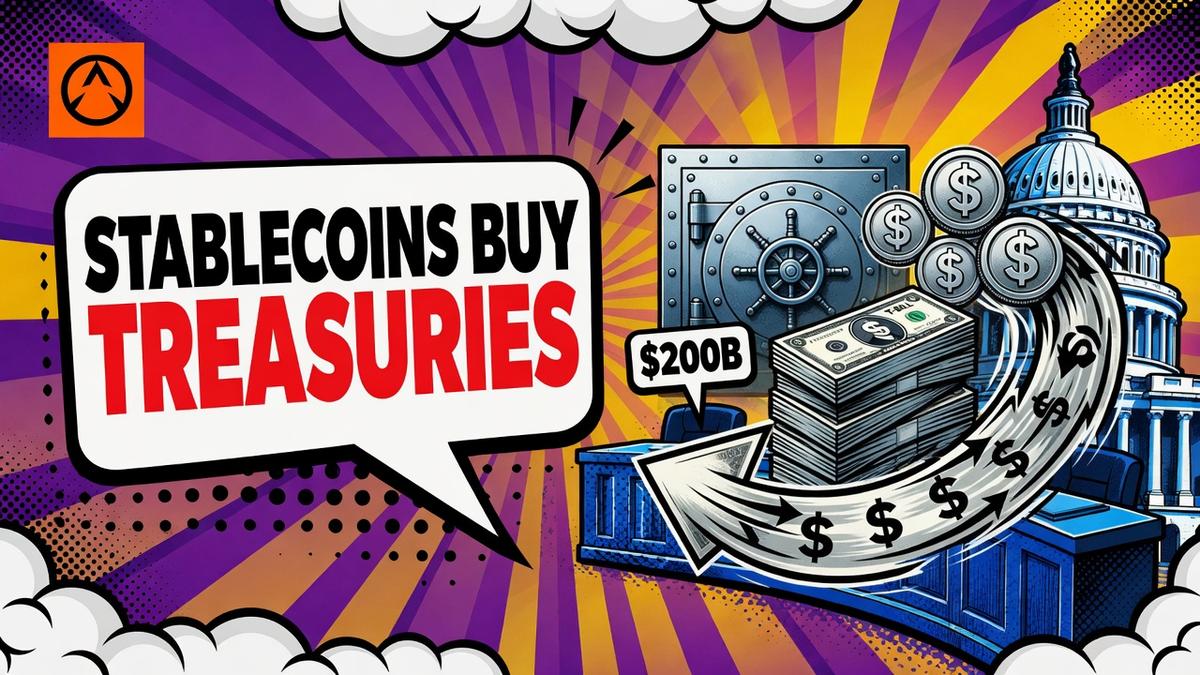
Stablecoin issuers have become a significant source of demand for US Treasuries. An SF Fed study says their holdings grew by about $200 billion over five years, equal to more than 40% of China's decline over the same period.
The two groups are not making the same kind of investment. China has reduced its holdings of longer-term debt, while stablecoin issuers have increased their holdings of short-term Treasuries.
A New Kind of Buyer for US Debt
Stablecoin issuers have been building Treasury reserves alongside the stablecoins they issue. Their holdings grew more than tenfold over five years, largely outpacing the growth in Treasury bills held by foreign governments.
Tether and USD Coin, known as USDC, account for more than 80% of stablecoin market capitalization as of mid-August 2026. Their issuers' Treasury holdings have grown more than tenfold over the same five-year period. That concentration gives two companies an outsized role in where this new demand is going.
Since 2023, stablecoin issuers have increased their short-term Treasury holdings by more than Japan, the largest foreign holder of US debt. Japan still holds more overall. The change is in how quickly issuers have added bills at the short end of the market.
The broader shift is larger. Foreign holdings of US debt fell from more than 50% around 2008 to roughly 30% in early 2026. Foreign governments' share of foreign Treasury demand dropped from nearly 100% in the 1970s to just above 40% by early 2026.
Stablecoins are becoming part of the mix holding that market together.
Why Short-Term Bonds Matter
Treasury bills mature within a year. For stablecoin issuers, they offer a liquid asset that can back tokens designed to remain close to the value of the dollar.
The GENIUS Act, adopted in 2025, requires approved domestic issuers to back stablecoins one for one with high-quality liquid assets such as Treasury bills. The backing rule gives the asset choice a regulatory purpose, although the study does not say every stablecoin follows this framework.
This is where tokenized cash starts to resemble a bridge between crypto markets and public debt. Someone who buys a dollar-backed stablecoin is indirectly holding a claim tied to the issuer's reserves. The Treasury itself does not see the stablecoin buyer as its customer, but demand from the issuer can still support purchases of short-term government debt.
Stablecoin activity is also more international than its image sometimes suggests. Relative to GDP, usage is highest in Africa, the Middle East and Latin America, and most transactions cross a border. For those payments, stablecoins offer a way to move dollar value without relying entirely on the traditional banking path.
$400 Billion Is Possible, but Uncertain
The SF Fed authors project that stablecoin demand for short-term Treasuries could roughly double to about $400 billion by the end of 2030. That is their extrapolation of the recent growth trend, not a settled forecast.
The outcome depends on who buys the stablecoins. New investors who do not already hold Treasuries would add demand for US debt. Existing Treasury holders using stablecoins as an indirect route would mostly change how they hold the same exposure. Those are very different outcomes for Treasury buyers.
The projection also depends on regulation around the world, competing products and bank-led cross-border payment technology. Even at $400 billion, the authors say stablecoins would remain a small part of US government financing needs.
There is another reason not to treat the figure as guaranteed. If a larger pool of private investors viewed US debt as riskier, they might demand a higher yield to hold it. More stablecoin demand could increase the market's exposure to shifts in confidence, rather than simply provide steady funding.
What Changes, and What Does Not
Stablecoin issuers have already become a buyer worth watching. Their $200 billion increase shows how quickly Treasury demand can grow alongside dollar tokens used in crypto markets and international payments.
It does not replace Chinese holdings one for one. The maturities differ, the buyer base differs and the scale remains smaller than the US government's financing needs. What it does is make Treasury demand more connected to crypto settlement.
That link may become more important if the market approaches the study's $400 billion projection. It may also grow more slowly if regulation limits adoption, competing payment systems keep their edge or stablecoins mostly attract investors who already wanted Treasuries.
The safest conclusion is measured. Stablecoins are already shaping demand at the short end of the US debt market. Whether they bring in genuinely new buyers of dollars is the detail that matters next.
Pallavi Malviya Gupta
Pallavi Malviya Gupta is the COO of Altcoin Buzz and founder of Funjible Games. Based in Singapore, she's been with Altcoin Buzz since its early days. Pallavi brings a builder's eye to both crypto media and gaming, she's spent years watching both spaces grow from niche communities into mainstream industries and still gets genuinely excited when something's built well.
More from PallaviNext up
Visa Opens Its Settlement Network to Anchorage Digital's Stablecoins
Anchorage Digital Bank can now settle Visa network obligations in stablecoins it issues, starting with Western Union's USDPT, under a 12 November deal.
Securitize and Ethena Activate $100M Liquidity Facility for BlackRock’s BUIDL
DBS and Circle Bring 24/7 USDC Minting and Redemption to Asian Institutions
JPMorgan and DBS Bring 24/7 Tokenized Dollar Transfers Between the US and Singapore
Hyperliquid's Open Interest Jumped 80% in Q3: Can It Hold the Gain?
 HYPEUSDC