Strategy Bought More Bitcoin Last Week. Can It Keep Doing It?
Strategy retained billions in stock issuance capacity and flexible cash, but weaker market valuation has raised doubts about funding future Bitcoin buys.

By Pallavi Malviya GuptaChief Editor
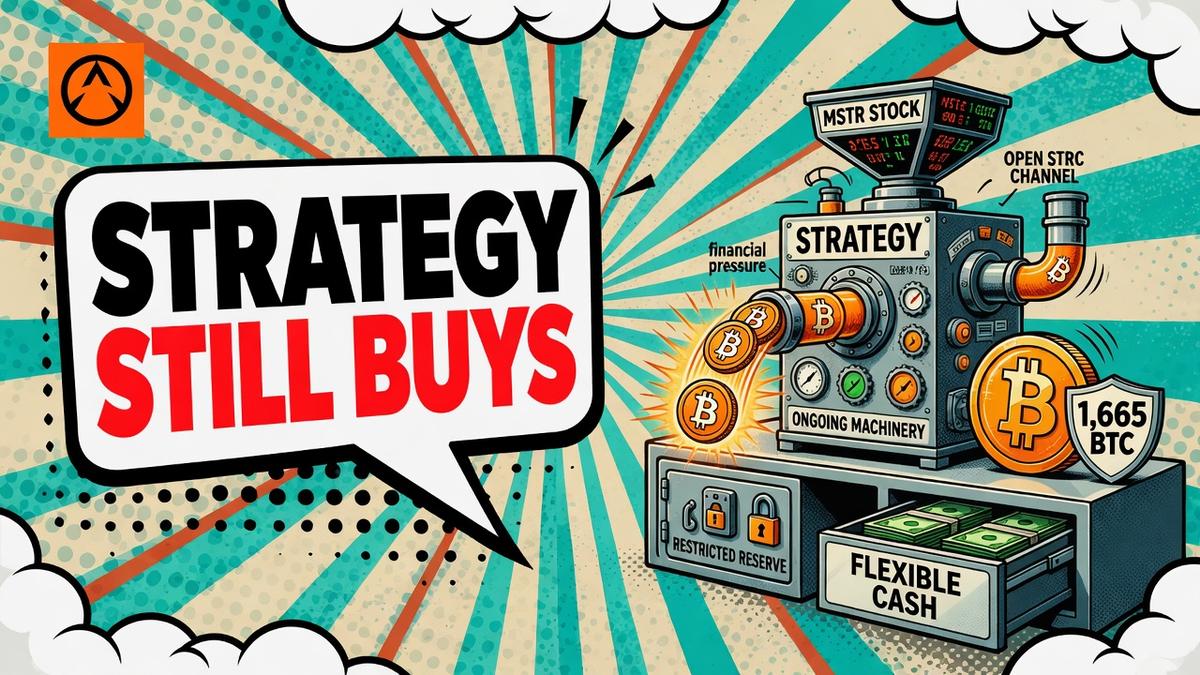
Peter Schiff says Strategy no longer has the machinery to buy more Bitcoin. The company’s filings tell a more measured story: its preferred-stock channel is open on paper, but its main engine, selling MSTR shares, has become less valuable.
That distinction matters. Strategy can still buy Bitcoin, as its purchase of 1,665 coins last week showed. Whether it can keep doing so comfortably is another question.
The Bitcoin Buying Continued
Strategy spent $142.7 million from common-stock sale proceeds on 1,665 Bitcoin in the week ending September 27. The average purchase price was $85,681, including fees and expenses. Its holdings reached 847,666 BTC, at an aggregate cost of $63.95 billion.
The company’s weekly disclosure shows that this wasn’t an old habit being dusted off. It was an active funding route, even if a smaller one than before.
Strategy sold 1,469,165 MSTR shares during the same week and received $246.2 million in net proceeds. It used $142.7 million for Bitcoin and $103.5 million to repurchase STRC. Common-stock financing therefore still reached both the Bitcoin treasury and the preferred-stock market.
Schiff’s point is therefore too broad as a description of September. The machinery was still turning.
Saylor, meanwhile, pointed to calmer trading in the stock. As of October 2, he said STRC’s 30-day historical volatility was 9%, below the 10% recorded by the SPDR S&P 500 ETF (SPY).
STRC Funding Was Available, but Unused
Schiff argued that Strategy could no longer sell Stretch preferred stock, known as STRC, and had therefore lost a route to financing Bitcoin purchases. Yet Strategy’s September 28 filing still showed $17.51 billion available for issuing and selling STRC. No shares were sold during that week.
Availability doesn’t guarantee sales. Investors need to be willing to buy the shares, and Strategy pays STRC a 12% annual dividend. About $10 billion was outstanding in late July, so each new sale also brings more dividend obligations.
Strategy did last sell STRC through its at-the-market program between May 11 and May 17, generating about $1.95 billion, according to the report carrying Schiff’s comments. That figure wasn’t independently checked against a filing for this review.
Still, unused capacity can’t be described as gone. It may simply be less attractive.
Cash Is Split Into Two Different Pools
Strategy reported $6.02 billion in designated dollar assets as of September 27: $5.02 billion in its USD Reserve and $1.00 billion in USD Cash.
The distinction is important. The reserve is restricted to supporting preferred dividends and debt interest. USD Cash is the flexible pool available for Bitcoin purchases.
That means the $5.02 billion reserve is not ready cash sitting beside the Bitcoin buying account. The available $1.00 billion is the more useful number when judging immediate purchasing room.
Even the flexible pool does not remove every constraint. During the week, Strategy used $48.1 million of USD Cash for STRC repurchases and $22.1 million from its reserve to pay preferred dividends. It also spent $142.7 million of common-stock proceeds on Bitcoin.
The Real Pressure Comes From MSTR
The more important change is in Strategy’s common stock. Standard Chartered calculated in July that its market-to-net-asset valuation had fallen to roughly 1.0, from a peak of 3.4 in November 2024.
That valuation measures how much investors are paying for Strategy’s stock relative to the value of its Bitcoin holdings. When it falls toward 1.0, each dollar of newly issued stock brings in less capital for the treasury. It doesn’t stop the programme, but it can make the share-to-Bitcoin route less attractive.
Strategy has also changed how it protects that treasury. Between May and August, it sold 6,948 BTC for roughly $432.5 million, averaging about $62,250 per coin. A Digital Credit Capital Framework now authorizes up to $1.25 billion in Bitcoin sales to fund dividends and preferred-share buybacks.
That is a notable change for a company famous for never selling Bitcoin.
A Smaller Engine, Not an Empty Tank
Strategy had about $18.84 billion of MSTR issuance capacity and $17.51 billion of STRC capacity as of late September. It also retained $1.00 billion in flexible cash. The verified evidence does not support the claim that it had lost its Bitcoin-buying capacity.
What it may be losing is the easy, repeatable funding model that helped build a much larger Bitcoin position. Common-stock issuance is less valuable at a lower market-to-net-asset valuation, preferred dividends remain due, and much of the reported dollar reserve is reserved for obligations.
Strategy bought Bitcoin again in September. The next question is whether it can keep funding those purchases without leaning harder on shareholders, selling more stock below the value of its Bitcoin holdings or using treasury coins to meet other costs.
That is a narrower and more credible concern than saying the machinery is gone. It is running, but it no longer looks effortless.
Pallavi Malviya Gupta
Pallavi Malviya Gupta is the COO of Altcoin Buzz and founder of Funjible Games. Based in Singapore, she's been with Altcoin Buzz since its early days. Pallavi brings a builder's eye to both crypto media and gaming, she's spent years watching both spaces grow from niche communities into mainstream industries and still gets genuinely excited when something's built well.
More from PallaviNext up
Zoom, CNN & Ledger Caught in Major Crypto Malware Attack Across 178 Sites
Malicious JavaScript served via Optimizely reached visitors of 178 organisations on 16 November 2026, including Ledger, swapping crypto wallet addresses.
 BTC
 ETH
Bitcoin Plunges By 13% Outside Typical Ranges: What Drove The Drop?
BTC
Bitcoin Holds Near $64K as ETF Flows Turn Positive and Fed Hike Bets Climb
BTC
Crypto News Today: Russia's Crypto Shift, Institutional ETF Moves and Trezor Data Breach
BTC
Why Is Bitcoin Still Near $64K After a $230 Billion Rout?
BTC

