AltcoinBuzzAltcoinBuzz
Subscribe
  • Crypto News
  • Crypto Research
  • Technical Analysis
AltcoinBuzzAltcoinBuzz

An independent digital media outlet delivering crypto research, news, and technical analysis to a community of 600,000+ users.

Follow us on:

Discover

  • Crypto Research
  • Crypto News
  • Technical Analysis
  • Key Opinions
  • Upcoming Launches

Categories

  • Bitcoin BTC
  • RWA
  • Technology
  • Altcoins
  • Regulation

Company

  • Affiliates
  • Partners & Sponsors
  • Careers
  • Contact
  • Terms of Use
  • Subscription Terms
  • About the ALTCOIN BUZZ
  • Privacy Policy
  • Contact ALTCOIN BUZZ
  • Advertise with us

Copyright 2026 ALTCOIN BUZZ. All rights reserved.Something is buzzzzzzzing.
HomeCrypto ResearchStablecoin Issuers Added $200 Billion in Treasury Holdings
Crypto ResearchStablecoinsRWA

Stablecoin Issuers Added $200 Billion in Treasury Holdings

Tether and Circle added about $200 billion in Treasury and repo holdings, but the assets do not directly replace China at the long end.
SShitij Gupta•Oct 3, 2026
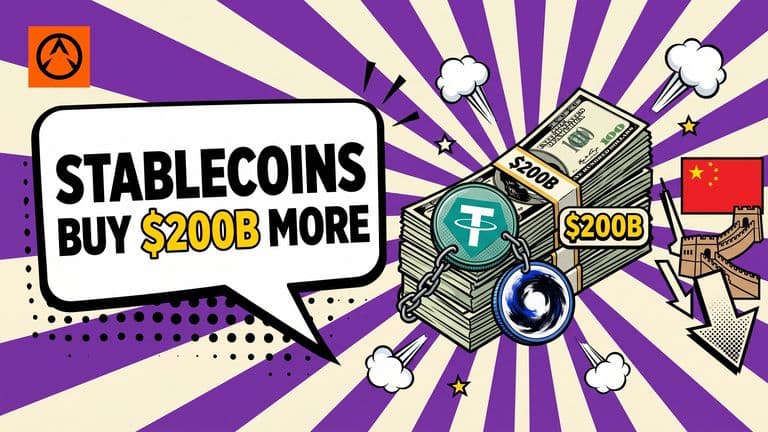
A pop-art cover shows USDT and USDC coins beside an expanding stack of US Treasury bills, with a separate downward path indicating China’s declining holdings.

Tether and Circle increased their Treasury and repurchase-agreement holdings by about $200 billion over five years, equivalent to more than 40% of the decline in China’s US Treasury holdings over the same period, according to San Francisco Fed researchers.

The comparison measures the scale of two opposite flows, not a direct handover of reserves. It also leaves a maturity gap: China reduced its holdings, mostly at the long end, while stablecoin issuers primarily bought Treasury bills and other short-maturity assets.

What the $200 Billion Comparison Measures

The researchers put the stablecoin issuers’ increase in Treasury securities and repurchase agreements against China’s reduction in Treasury holdings over five years. The $200 billion represented more than 40% of the Chinese decline, whose exact dollar value was not provided in the available summary.

That is a comparison of aggregate changes. It does not show that reserves released by China moved into stablecoins, or that the two investors bought the same securities.

The maturity difference matters. China’s reductions were concentrated largely in longer-dated debt. Stablecoin issuers predominantly buy Treasury bills and other highly liquid, short-maturity assets. A larger bill market does not necessarily create an equivalent buyer for longer-term notes and bonds.

The underlying research, the Federal Reserve Bank of San Francisco’s Stablecoin Issuers’ Growing Appetite for Treasury Securities, describes stablecoin holdings as having partly offset weaker demand from some foreign governments. It also says their share of Treasury holdings remains relatively small. The Fed in Print page for the Economic Letter links to the underlying paper.

Tether and Circle Lead the Shift

Tether and Circle are the issuers behind USDT and USDC. Together, those tokens represented more than 80% of stablecoin market capitalization as of mid-August, according to the Fed researchers.

That market share identifies the two issuers driving the aggregate change, but it does not divide the $200 billion between them. No primary table confirming their individual reserve holdings was available for the report.

The growth has changed the issuers’ position in the Treasury market. Stablecoin issuers’ Treasury holdings have risen more than tenfold in five years, and since 2023 they have added more short-term Treasury holdings than Japan, the largest foreign holder of US government debt.

The San Francisco Fed said, citing Bank for International Settlements research, that stablecoin demand is large enough to measurably affect short-term government bond yields. The data supports a bill-market effect. It does not establish a matching influence over long-term borrowing costs.

Reserves Create Structural Demand for Bills

Approved US payment stablecoin issuers must fully back outstanding tokens with eligible liquid reserves under the GENIUS Act, adopted in 2025. Proposed implementing rules include Treasury bills, notes and bonds with remaining maturities of 93 days or less.

The reserve model also gives issuers an economic reason to hold those assets. Token holders generally receive none of the yield earned on the backing Treasuries, while the issuer can collect the interest.

That structure links stablecoin growth to demand for short-duration government debt. It does not require stablecoin issuers to hold long-dated notes or bonds, so their expansion cannot be treated as a full substitute for every category of foreign demand.

The broader shift is visible in the ownership of US debt. Foreign investors held more than half of outstanding Treasuries around 2008, compared with roughly 30% by early 2026. Foreign governments accounted for just over 40% of foreign Treasury demand by early 2026, down from nearly all at the peak of that demand in the 1970s.

The $400 Billion Scenario Is Conditional

The Fed researchers project that stablecoin issuers’ demand for short-term Treasuries could nearly double to more than $400 billion by the end of 2030. That is a conditional scenario based on the recent growth trend continuing, not a forecast anchored to a scheduled adoption target.

The researchers attached substantial uncertainty to the estimate. Regulation outside the US, competing payment products and new bank technology could slow stablecoin adoption. A continuation of the recent reserve trend would be needed to support the projection.

The current data establishes growing demand for liquid, short-term government assets from two issuers with a combined token market share above 80%. It does not establish that stablecoins are replacing China as a long-term creditor to the US, or that their reserves directly measure incremental crypto-market risk appetite. The $400 billion case depends on whether the recent growth in issuer reserves persists.

The information discussed by Altcoin Buzz is not financial advice. This is for educational, entertainment, and informational purposes only. Any information or strategies are thoughts and opinions relevant to the accepted levels of risk tolerance of the writer/reviewers and their risk tolerance may be different than yours. We are not responsible for any losses that you may incur as a result of any investments directly or indirectly related to the information provided. Bitcoin and other cryptocurrencies are high-risk investments so please do your due diligence.

Copyright Altcoin Buzz Pte Ltd.

Related

A comic style illustration of a crossroads with a bank building on one path and blockchain blocks on the other. A coin rests at the fork. A speech bubble sits on the left.
RegulationKey Opinions
Oct 7, 2026

Hyperliquid Policy Center CEO Says Exchanges Need Public Blockchains to Stay Competitive

Jake Chervinsky and Rebecca Rettig argue in Fortune that Wall Street must build on public blockchains or lose customers, and explain what the GENIUS Act does.

HYPESOL
Anmol Billa
A comic-style balance scale with one large lightning-marked XRP coin outweighing a few small diamond tokens on one side and two gold Ethereum coins on the other, beside a speech bubble reading ONE TOKEN CARRIES XRPL.
RWAAltcoins
Oct 7, 2026

XRPL's Tokenized Commodity Lead Rests on One $2.2B Energy Token

The XRP Ledger leads tokenized commodities through one Justoken energy asset worth $2.23 billion. Count gold by value and Ethereum's commodity pile is larger.

XRPRLUSD+1 more
Saloni Rathi
Comic-style illustration of a cracked vault door with an Ethereum coin on it, a gloved hand siphoning coins out through a pipe while an open padlock hangs from the door.
DeFiEthereum ETH
Oct 6, 2026

Flash Loan Attacks Drained $1.2B From DeFi, Study Finds

A study in the Journal of Financial Crime counted 72 flash loan attacks among 254 DeFi exploits, with losses of $1.211 billion. Here is what the numbers cover.

ETH
Anmol Billa